The broker strongly favors semiconductor equipment stocks, especially those with high storage exposure, expecting a 3-5 year period of rapid order growth and citing rare valuation discounts versus global peers.
Kaiyuan Securities strongly favors a turnaround in the medical equipment sector, highlighting robust 3Q26 tender data and naming several leading companies as key beneficiaries.
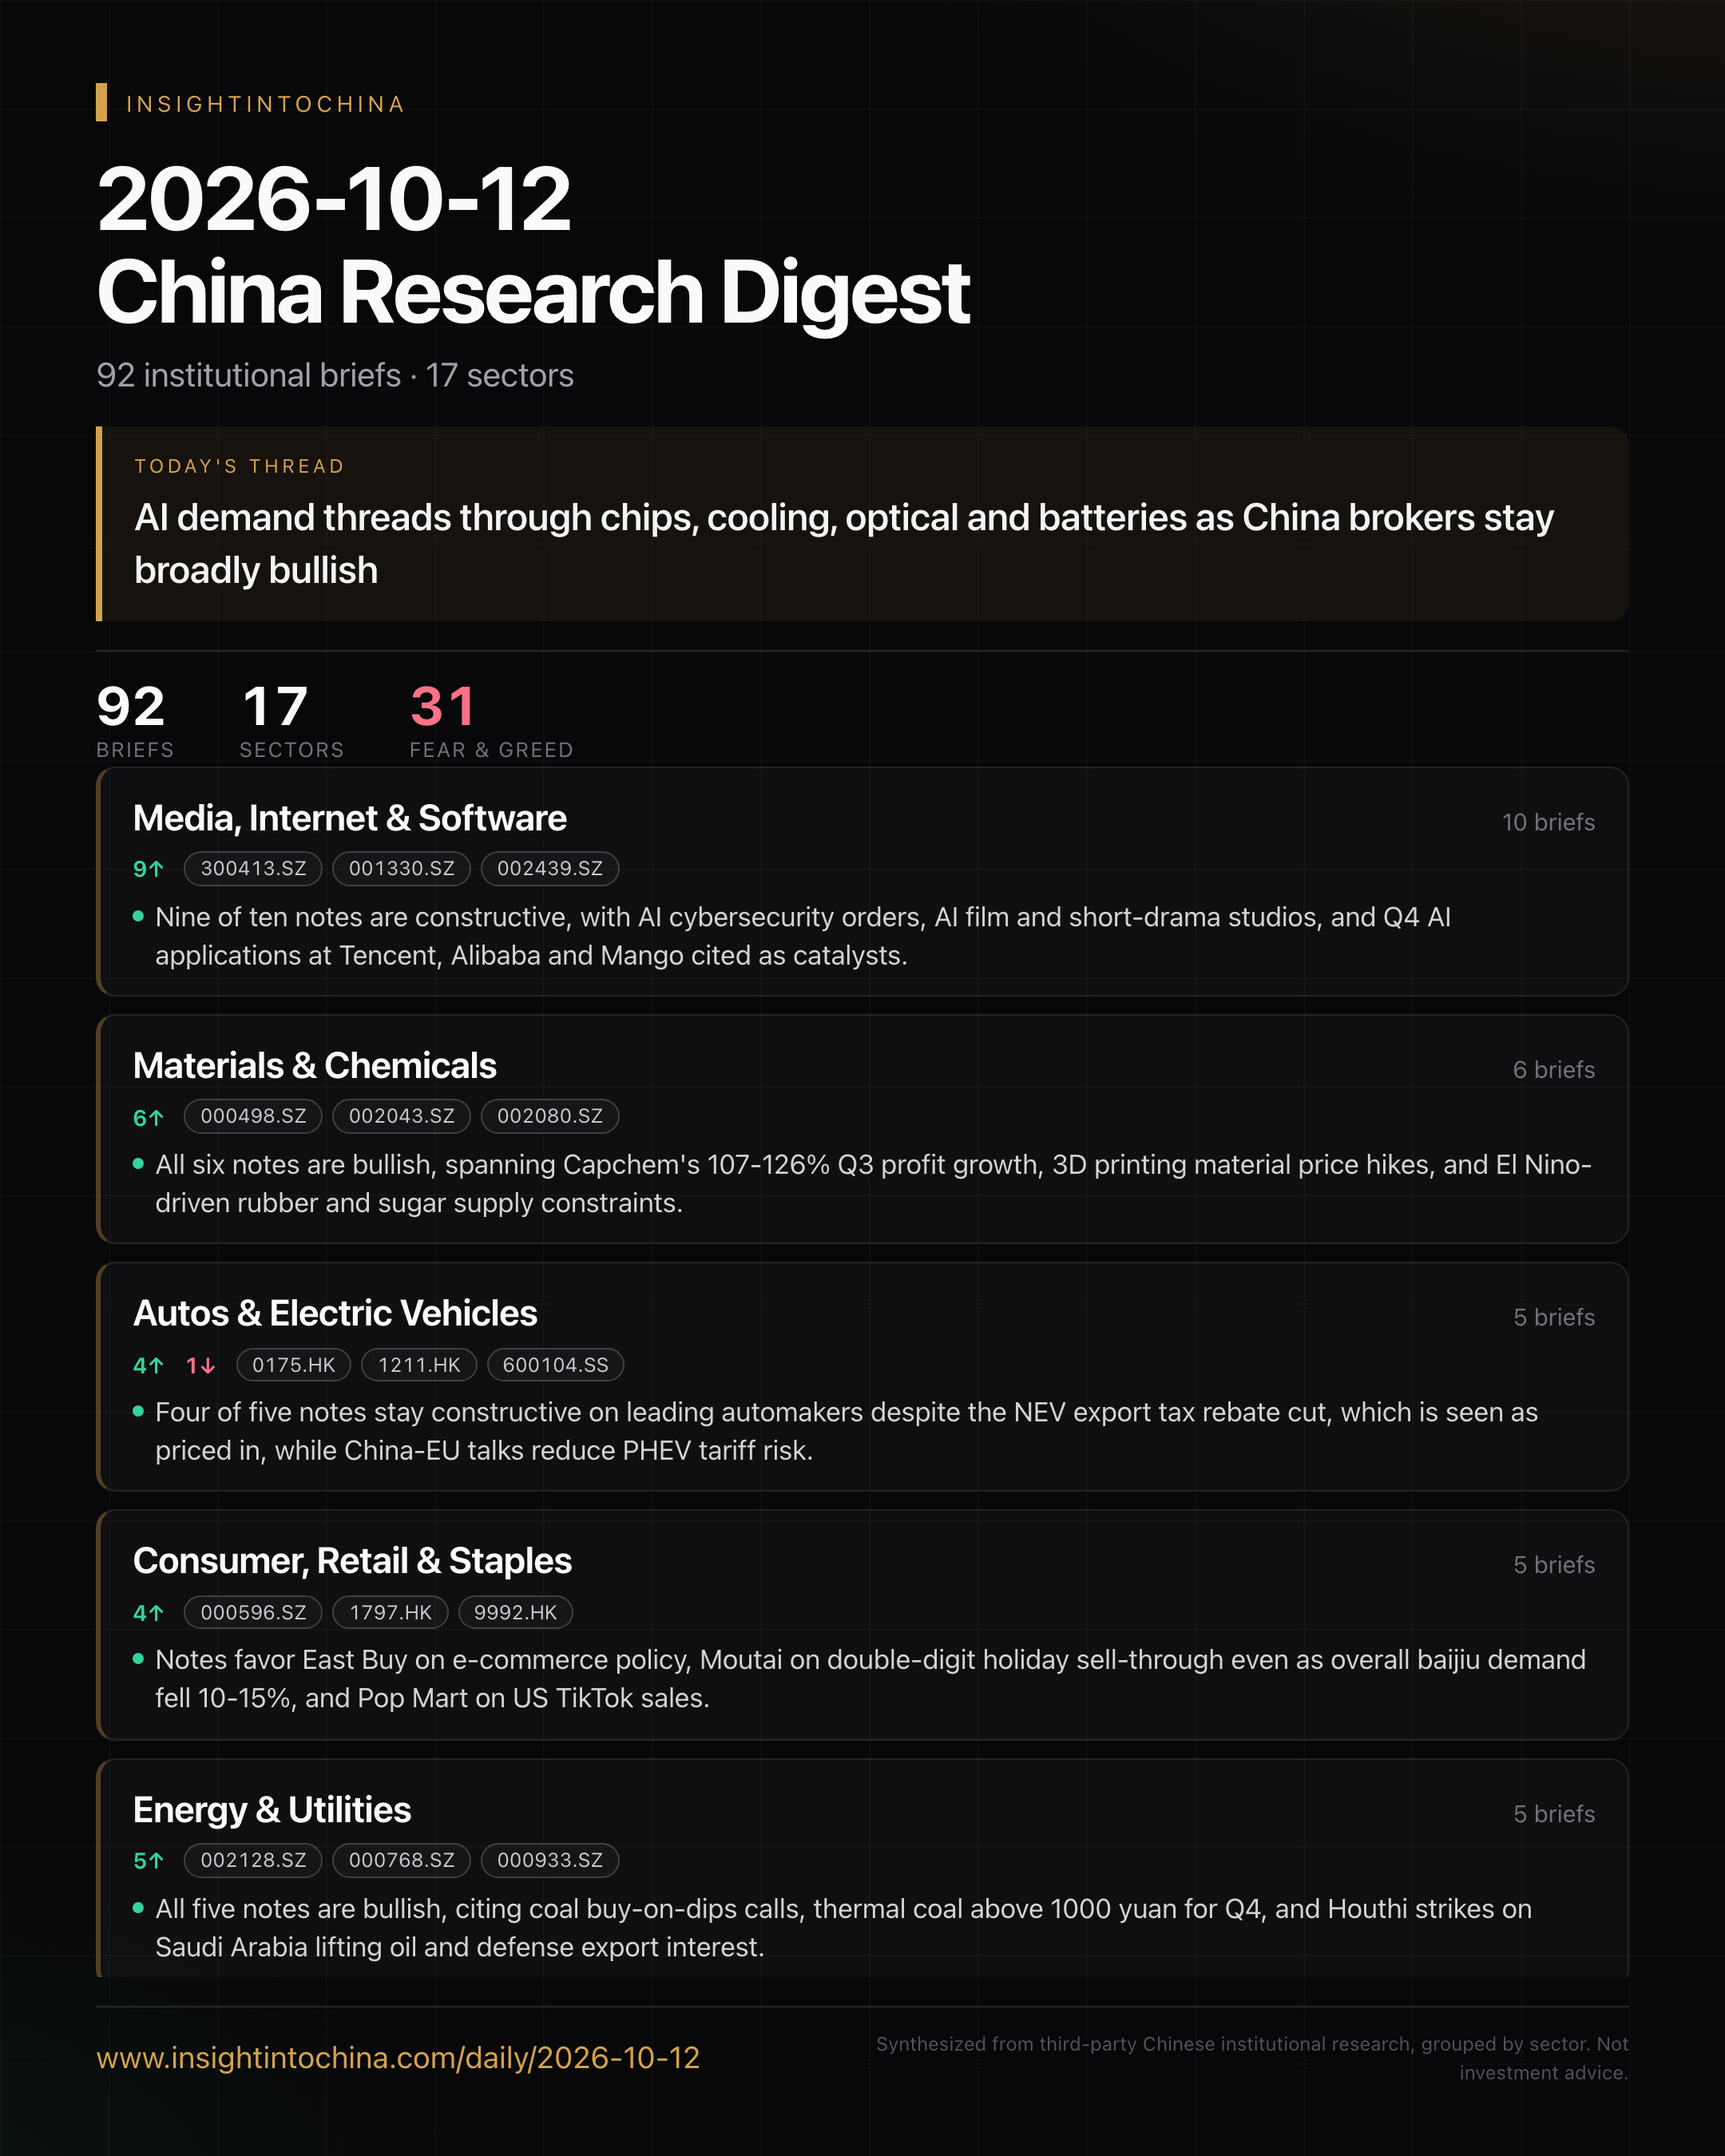
The broker maintains a constructive view on the AI film and AI+IP themes, recommending investors watch companies with mature content production and platform distribution capabilities.
Capchem's Q3 2026 earnings preview shows robust YoY and QoQ growth, with all business segments firing and expansion projects underway, supporting a bullish outlook.
Huaxin Chemical strongly recommends Jindan Technology as a top pick in the 3D printing materials sector, citing supply-demand tightening and recent price hikes.
The NEV export tax rebate reduction is a known negative now materializing, but CITIC remains bullish on leading Chinese automakers' overseas expansion and advises accumulating on weakness.
The China-EU trade friction is less severe than feared, but not fully resolved; policy details expected mid-month will determine the extent of the benefit for PHEV exporters.
Baijiu holiday demand missed expectations, but Moutai's double-digit sell-through growth and inventory destocking keep the broker constructive on Moutai, Jinshiyuan, Gujing and Yingjia.
Geopolitical tensions are driving oil prices higher and increasing demand for Chinese military exports, with several A-share defense names cited as beneficiaries.
Kaiyuan Securities strongly favors a turnaround in the medical equipment sector, highlighting robust 3Q26 tender data and naming several leading companies as key beneficiaries.
The broker is bullish on China's medical device sector, citing policy normalization, innovation, and global expansion as key drivers for a valuation rebound.
CSC remains bullish on APT Medical, expecting Q3 growth to continue on PFA ramp-up and viewing the upcoming Fujian EP procurement renewal and equity incentive targets as positive catalysts.
Dongwu Securities strongly recommends buying leading lithium battery and material companies, expecting a sector rebound driven by trade de-escalation, Q3 earnings growth, and low valuations.
The broker strongly favors semiconductor equipment stocks, especially those with high storage exposure, expecting a 3-5 year period of rapid order growth and citing rare valuation discounts versus global peers.
Rendong Holdings is advancing its AI strategy through a strategic investment in Taichu Integrated Circuit, reinforcing its 'payments + AI' ecosystem vision.
Broker sentiment is bullish on Yunyi Electric as a low-cost, high-option-value play on the global SOFC build-out, with the main business providing downside support.
Broker sees opportunity in pessimism for China's optical module sector, expecting an October rebound and favoring oversold leaders and second-tier players.
Broker is bullish on China's optical component sector, particularly MPO connectors, with JPT and Broadex as key beneficiaries of AI-driven demand and favorable supply dynamics.
China Jushi's robust Q3 results and ongoing electronic fabric price momentum support a bullish outlook, with potential upside from specialty fabric certification.
Western Bank advises a defensive tilt in bank stocks, recommending accumulation of state-owned large banks, top joint-stock banks, and quality city commercial banks.
China Merchants Machinery is bullish on the construction machinery sector, citing a Q3 earnings inflection, resilient demand, and compelling 2027 valuations.
The broker maintains a bullish view on China property stocks, recommending quality developers and second-hand housing agencies as core city fundamentals improve.
CITIC Securities remains bullish on gold and copper, expecting copper equities to close the performance gap and the metals sector to offer better returns ahead.
The broker maintains a positive view on select Chinese gaming stocks, emphasizing AI platform potential and the resilience of leading titles despite an overall holiday revenue dip.
Goldman Sachs turns bullish on Asia-Pacific data center infrastructure enablers, emphasizing that execution bottlenecks will determine winners as capacity commitments scale.
Hongxin Electronics is seen as a key beneficiary of Nvidia's new compliant card cycle, with its Antonglian subsidiary's elite distributor status potentially driving significant revenue and profit growth.
Yuanjie Tech is poised for multi-fold earnings growth next year, driven by capacity expansion, product upgrades, and customer breakthroughs, with order visibility extending to 2028.
Tone percentile minus 20-day return percentile. Positive means the research
reads more positive than the price has been — it does not say which one is right.