The broker remains bullish on the diamond thermal management sector, expecting large-scale orders to materialize and recommending a list of Chinese stocks poised to benefit.
CITIC strongly recommends Dayuan Pump, expecting its dual Google-Nvidia customer ramp and UL certification to drive rapid earnings growth and a near-doubling of market cap.
The US 337 investigation into AI server VPD power is a patent enforcement action by Vicor that may lead to licensing deals, and the broker is bullish on Xinleineng as a domestic player with self-developed technology.
The broker recommends focusing on certainty and short-term catalysts in optical interconnect, naming Tianfu Communication, Changying Tong, Accelink, Linktel, Shijia Photons, Zhongji Innolight, and Eoptolink as key picks.
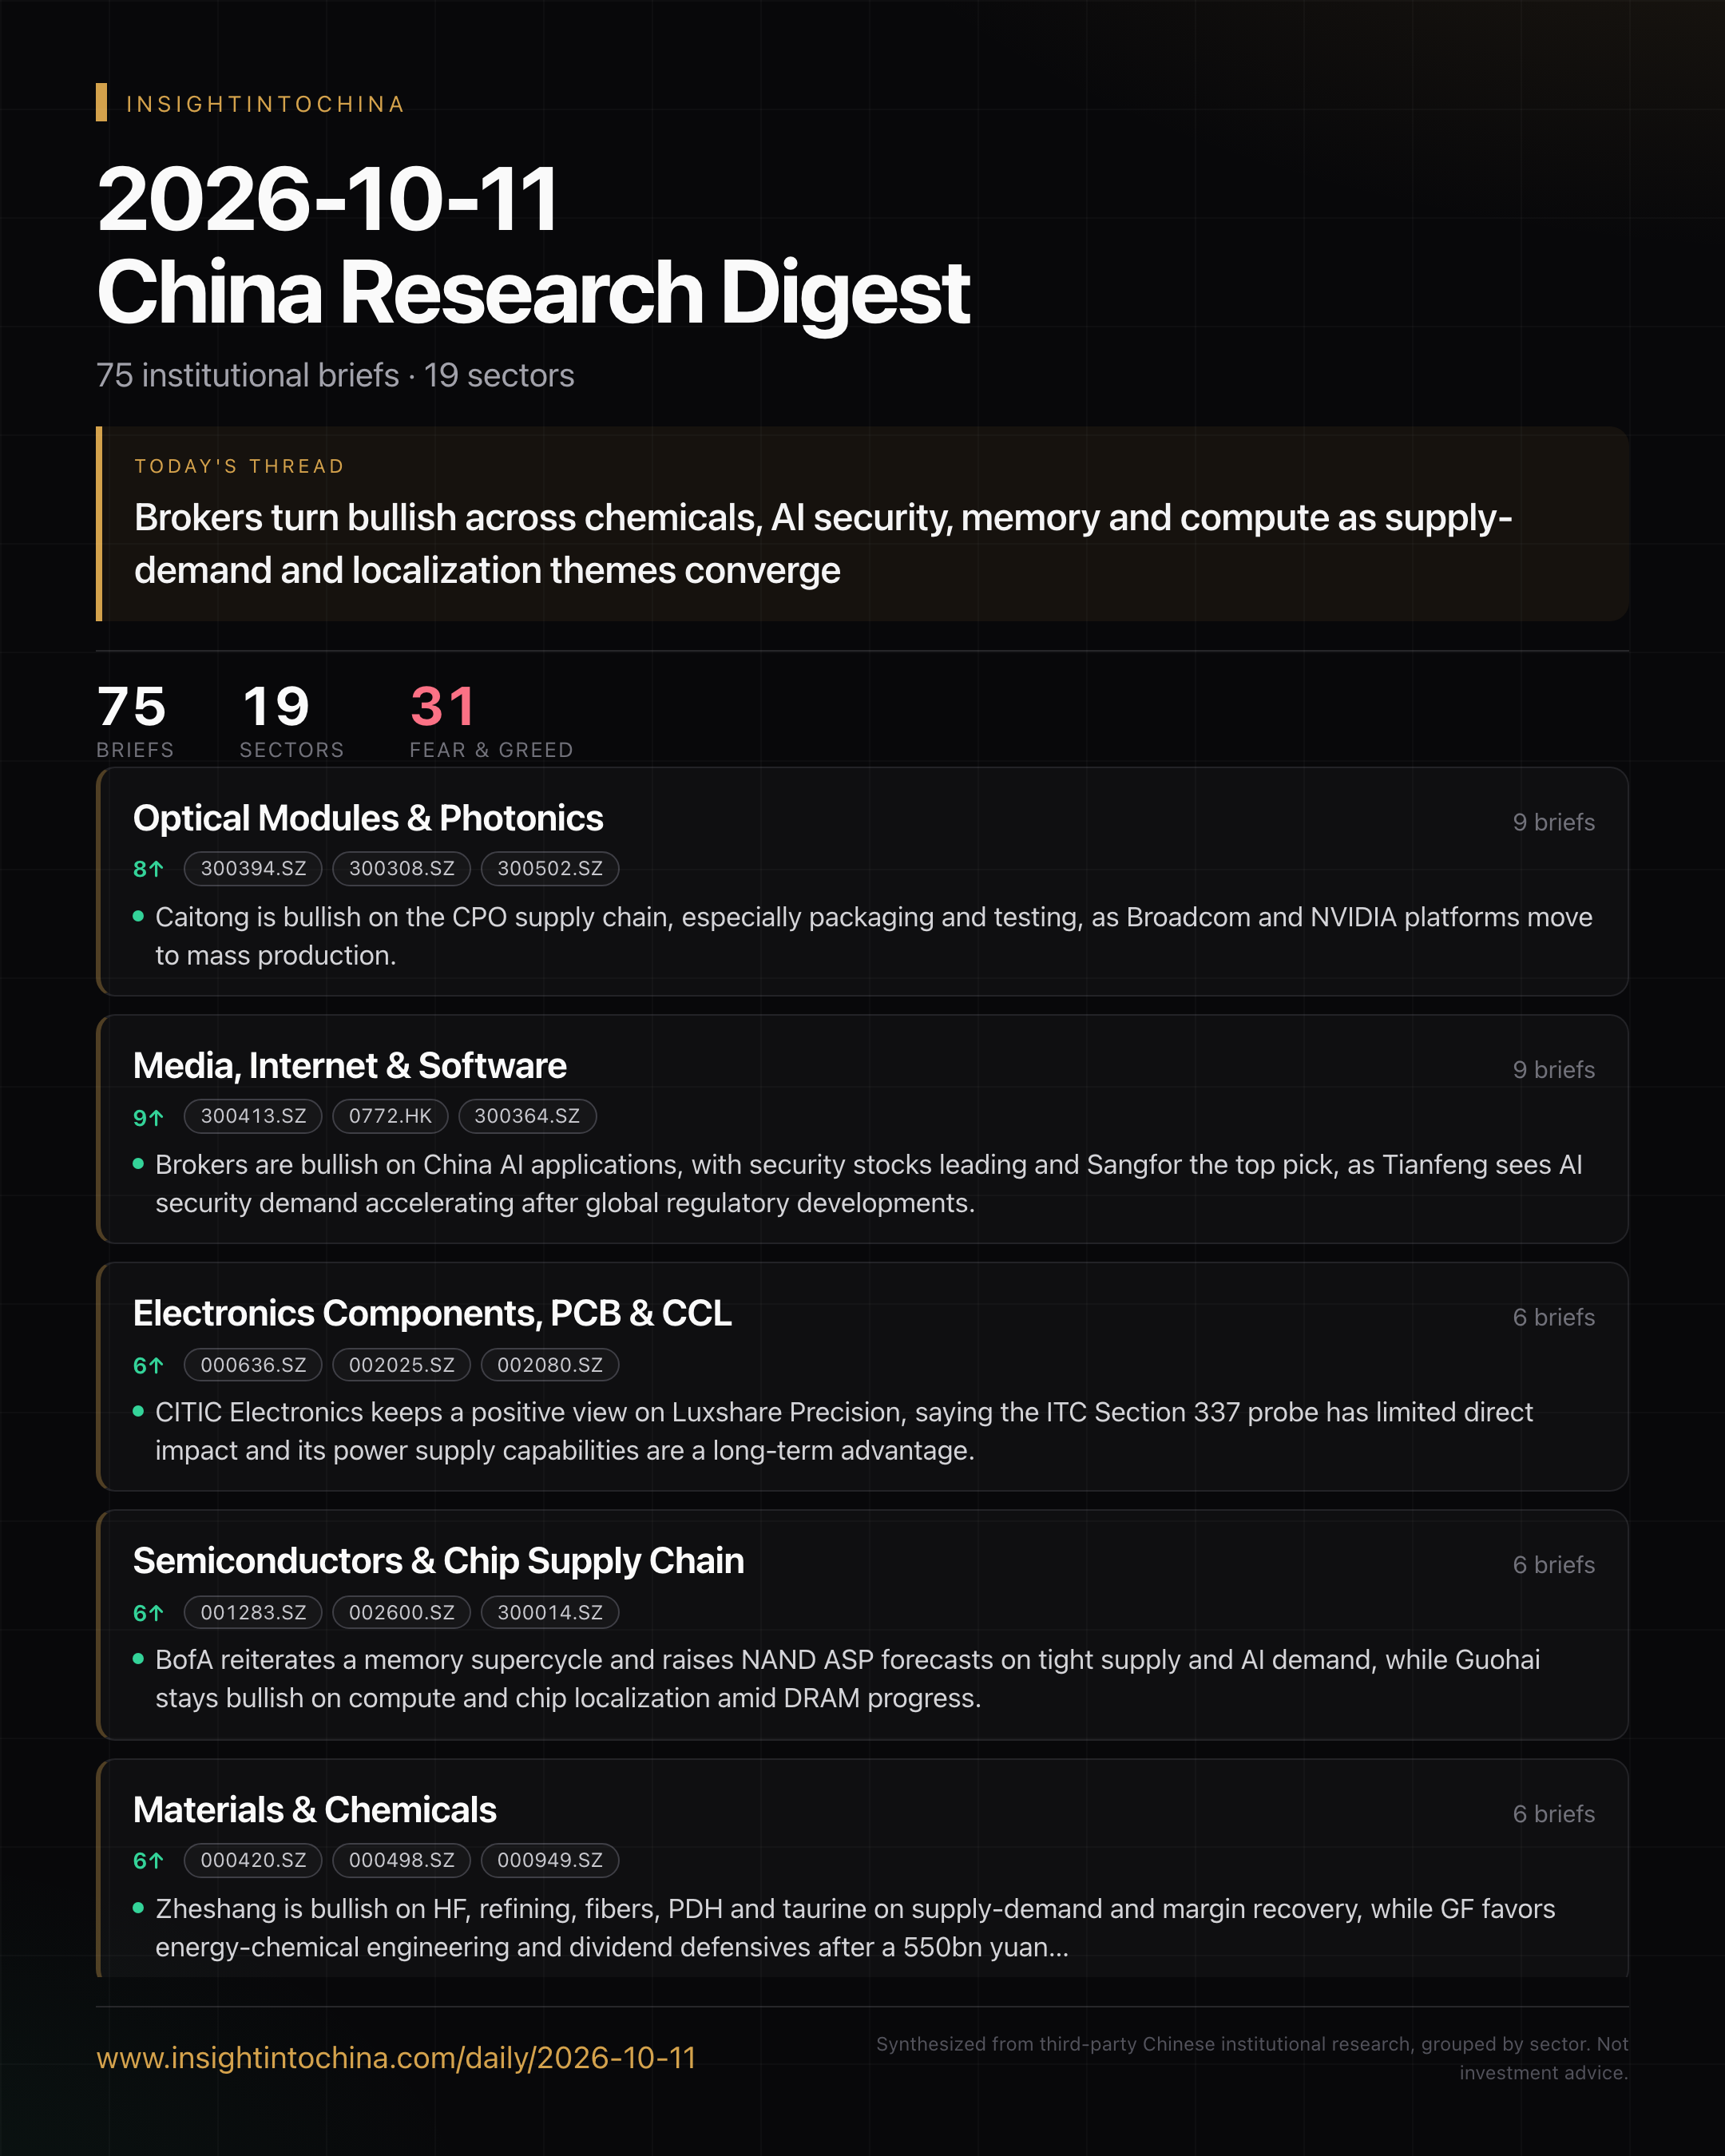
The broker is bullish on China's AI application sector, especially security stocks, with Sangfor as the top pick and NSFOCUS and Qilinsec as higher-beta plays.
Tianfeng sees AI security as an emerging growth driver for Chinese cybersecurity firms, with demand set to accelerate domestically following global regulatory and security developments.
The broker maintains a positive stance on China's AI video content sector, expecting Q4 catalysts and emphasizing the shift from traffic-driven to content-driven models.
CITIC Electronics maintains a positive view on Luxshare Precision, stating the ITC investigation has limited direct impact and the company's power supply capabilities are a long-term competitive advantage.
Guolian Minsheng remains bullish on the MLCC sector, recommending high-end Chinese manufacturers Sanhuan, Fenghua, Torch, and Hongda Electronics amid new price increases and AI demand.
The broker remains bullish on Kingboard Laminates, raising its target price to HK$96 on stronger-than-expected fiberglass fabric prices and a favorable relative valuation versus Kingboard Holdings.
Zheshang Securities is bullish on select Chinese chemical sub-sectors, citing supply-demand improvements and pricing trends, but provides no specific stock picks or quantitative targets in this summary.
The broker remains bullish on the diamond thermal management sector, expecting large-scale orders to materialize and recommending a list of Chinese stocks poised to benefit.
CITIC strongly recommends Dayuan Pump, expecting its dual Google-Nvidia customer ramp and UL certification to drive rapid earnings growth and a near-doubling of market cap.
The broker remains bullish on mass food and beverage stocks with growth and dividend characteristics, and recommends gradually accumulating baijiu positions.
Guolian Minsheng Auto maintains a 'Recommended' rating on Geely, citing the Galaxy Warship 700's competitive pricing and product strengths that fill a gap in Geely's high-value off-road SUV lineup.
Guosen Auto is bullish on the Robotaxi and smart driving sector, citing Tesla's accelerating Cybercab expansion as a sign that the commercialization inflection point is near.
United Energy Group offers high profit elasticity, strong dividend potential, and trades at a very low valuation, making it a compelling long-term opportunity.
The US 337 investigation into AI server VPD power is a patent enforcement action by Vicor that may lead to licensing deals, and the broker is bullish on Xinleineng as a domestic player with self-developed technology.
Binglun Environment is well-positioned to benefit from rising demand for data center cooling solutions, with a strong order book and improving product mix supporting a bullish outlook.
Zheshang Securities maintains a bullish view on large state-owned banks and wealth-management-focused banks, citing dense policy support that extends the sector's upward logic beyond pure defense.
Zhongtai Securities is bullish on China P&C Insurance, expecting regulatory tightening on non-auto insurance to reduce expense ratios and boost underwriting profits over 2026-28.
Morgan Stanley remains bullish on CATL, viewing the recent pullback as a buying opportunity driven by macro concerns rather than structural deterioration.
The China-EU consensus on PHEVs is a positive development that reduces trade friction and has a negligible impact on lithium battery demand, reinforcing a bullish stance on Chinese EV and battery exporters.
Shandong's higher nuclear power guaranteed price ratio reinforces a bullish outlook on China's nuclear sector, with CGN and CNNP recommended as key beneficiaries.
China's satellite internet and commercial space sectors receive positive technological and policy catalysts, while SpaceX advances its orbital and direct-to-cell capabilities.
CICC Medical remains bullish on China's innovative pharma and out-licensing theme, recommending focus on CXO, innovative drugs, AI life sciences, and medical devices ahead of Q3 earnings and ESMO.
The broker is bullish on Haiou Housing, betting that a Fuyao-backed asset injection of chip assets will unlock substantial value, with the stock currently trading at a fraction of peer Youxun's valuation.
CICC maintains earnings forecasts, ratings and target prices, recommending Mango Super Media and highlighting AI film/TV progress as a key catalyst for leading platforms.
The USITC Section 337 investigation is a significant positive for A-share power component suppliers, with Zhongfu Circuit as the top pick and Xinleineng also worth watching.