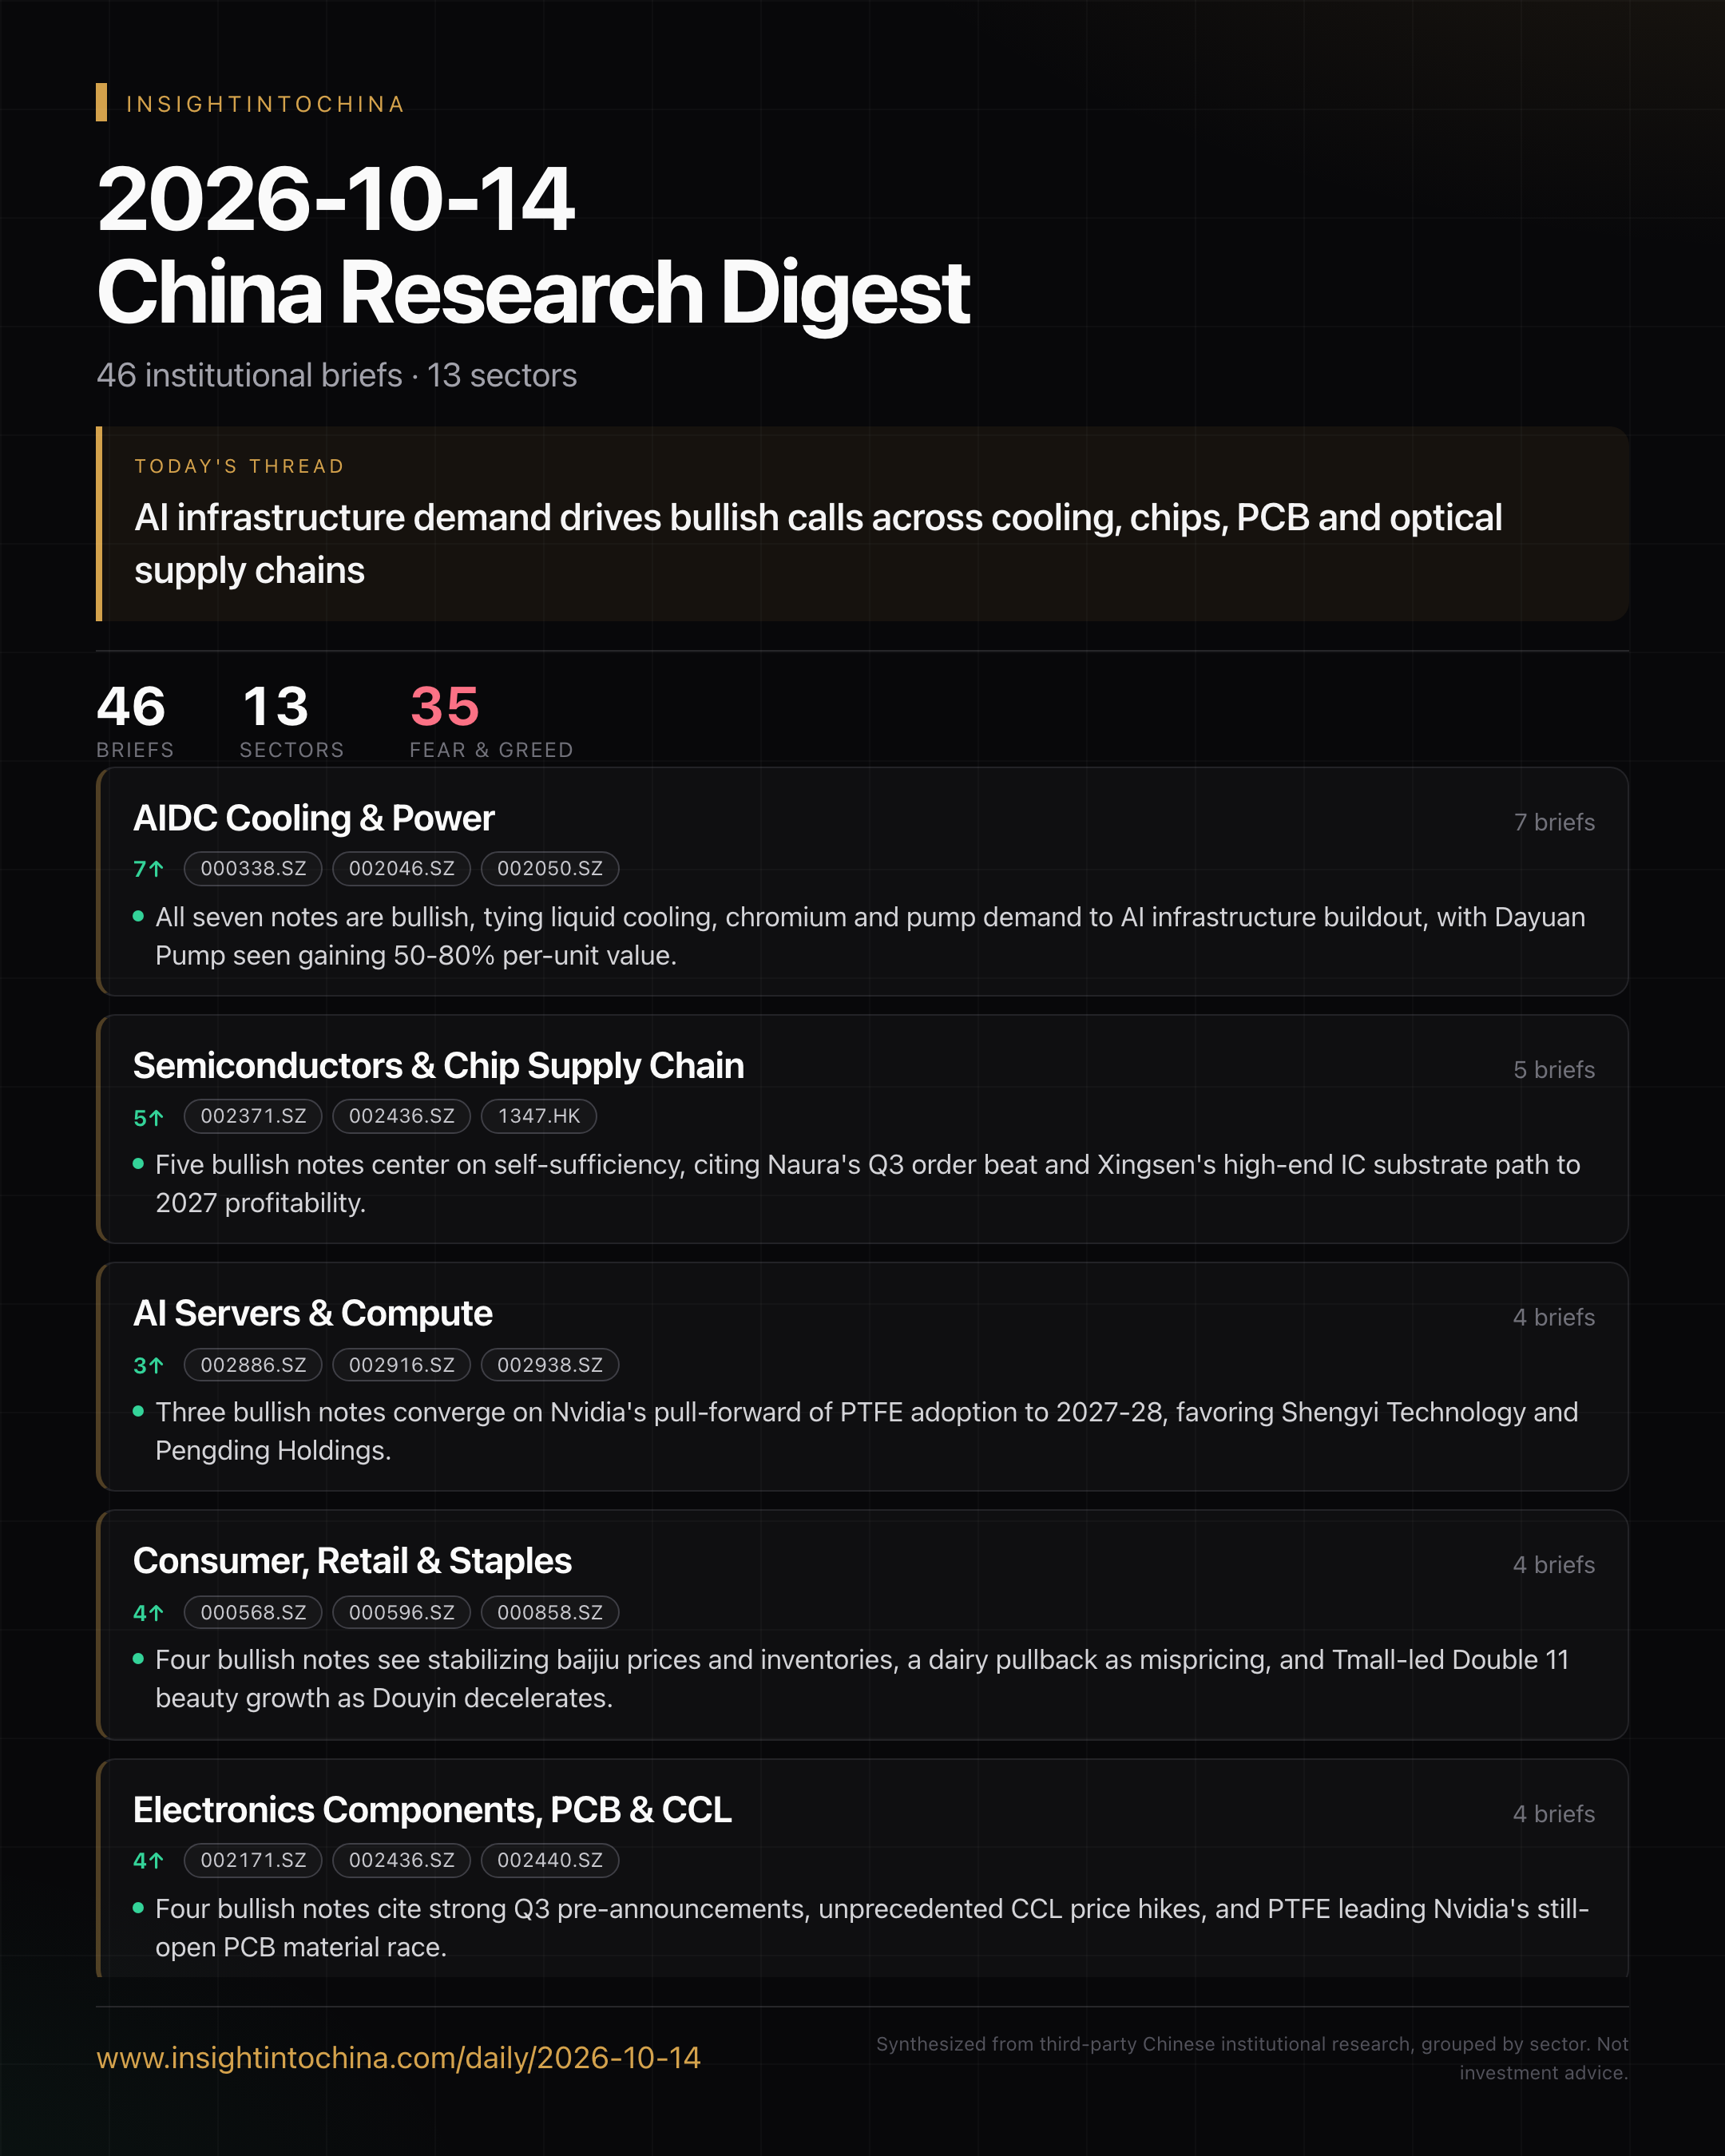
CMS Electronics remains firmly bullish on the PCB/CCL chain, citing strong Q3 results and unprecedented CCL price hikes as evidence of a multi-quarter upcycle.
Huaxi Machinery remains strongly bullish on China's semiconductor equipment sector, highlighting Naura's accelerating orders and recommending a broad list of domestic equipment names.
The broker strongly recommends focusing on the defense sector for Q4, with specific beneficiaries in large aircraft, military trade, and domestic demand.
CITIC is bullish on Dayuan Pump, citing dual demand drivers from Google and NVIDIA plus a 50-80% increase in per-unit pump value that should accelerate revenue and earnings growth.
Huaxi Machinery remains strongly bullish on China's semiconductor equipment sector, highlighting Naura's accelerating orders and recommending a broad list of domestic equipment names.
Xingsen Technology is positioning itself in the scarce high-end IC substrate space with a path to profitability by 2027, though risks around pricing and competition remain.
CSC Electronics is bullish on China's semiconductor self-sufficiency theme and recommends buying Hua Hong, Huafeng Test & Control, and Naura on Q4 weakness.
The broker is bullish on China's advanced electronic materials sector, citing accelerated PTFE adoption in Nvidia's Rubin Ultra as a catalyst for earnings and valuation upside across three supply chain themes.
The broker is bullish on the PTFE supply chain, particularly Shengyi Technology, as Nvidia moves toward glass-free PCB solutions for high-speed NVLink.
Baijiu holiday demand was unexciting but supply discipline is supporting prices and inventories, keeping the broker constructive on Moutai, Fenjiu, Jinshiyuan, Yingjia, Gujing and ZJLD.
The broker views the dairy stock pullback as a mispricing driven by temporary data noise, reiterates a bullish cycle call, and recommends Yurun, Modern Dairy, Yili, and New Hope Dairy.
Tmall's larger subsidies and 88VIP base support double-digit beauty growth, while Douyin's deceleration and traffic restructuring favor new domestic and international brands over legacy players.
CMS Electronics remains firmly bullish on the PCB/CCL chain, citing strong Q3 results and unprecedented CCL price hikes as evidence of a multi-quarter upcycle.
Weipai Ge's strategic move into PCB micro drills and Helin Micro-Nano's upcoming NVIDIA-driven order surge present bullish catalysts for both companies.
The broker maintains a bullish stance on the PCB materials sector, emphasizing that the PTFE solution remains the frontrunner but hydrocarbon alternatives are still in play, with domestic suppliers gaining traction in sampling and testing.
CITIC Securities is bullish on Highpower Technology, citing accelerating Q3 results and improving profitability from AI edge battery and energy storage businesses.
The broker sees a cyclical earnings recovery and overseas order-driven growth story in Chinese wind turbine makers trading at historically low valuations.
Broker sentiment is bullish on HyperStrong, citing a >20GWh order book, overseas margin of 20-25%, and a 2027 global storage demand doubling, with margin recovery expected in 2027Q1-Q2.
Morgan Stanley remains bullish on Zhongji Innolight, citing its pioneering optical interconnect products and strong financial outlook, with a target price implying 53% upside.
GF Securities reiterates a bullish stance on the optical communications sector, citing resilient 2027 demand and accelerating NPO adoption among hyperscalers.
Huatai views the export tax rebate cut as a manageable fiscal adjustment that favors high-priority sectors like autos and equipment, with limited overall tax impact.
The broker strongly recommends focusing on the defense sector for Q4, with specific beneficiaries in large aircraft, military trade, and domestic demand.
The broker's framework suggests investors should focus on automated capacity build-out and inspection capability when assessing Tesla Optimus supply-chain names, not on single-quarter revenue swings.
Fangzheng Mechanical is bullish on Kete Power, seeing export order spillover and high-margin overseas deliveries as key drivers of a 2026-2027 earnings recovery.