Yangjie Technology's Q3 earnings confirm a high-growth trajectory in power semiconductors, with automotive and SiC businesses doubling, supporting a bullish outlook.
Sieyuan Electric is well-positioned for sustained growth, with overseas orders surging and new products gaining traction, making it a compelling investment at current valuations.
Huachuang reiterates a Strong Buy on YTO Express, citing three underappreciated strengths—AI-driven cost reduction, franchisee ecosystem balance, and international air cargo potential—with 39% upside.
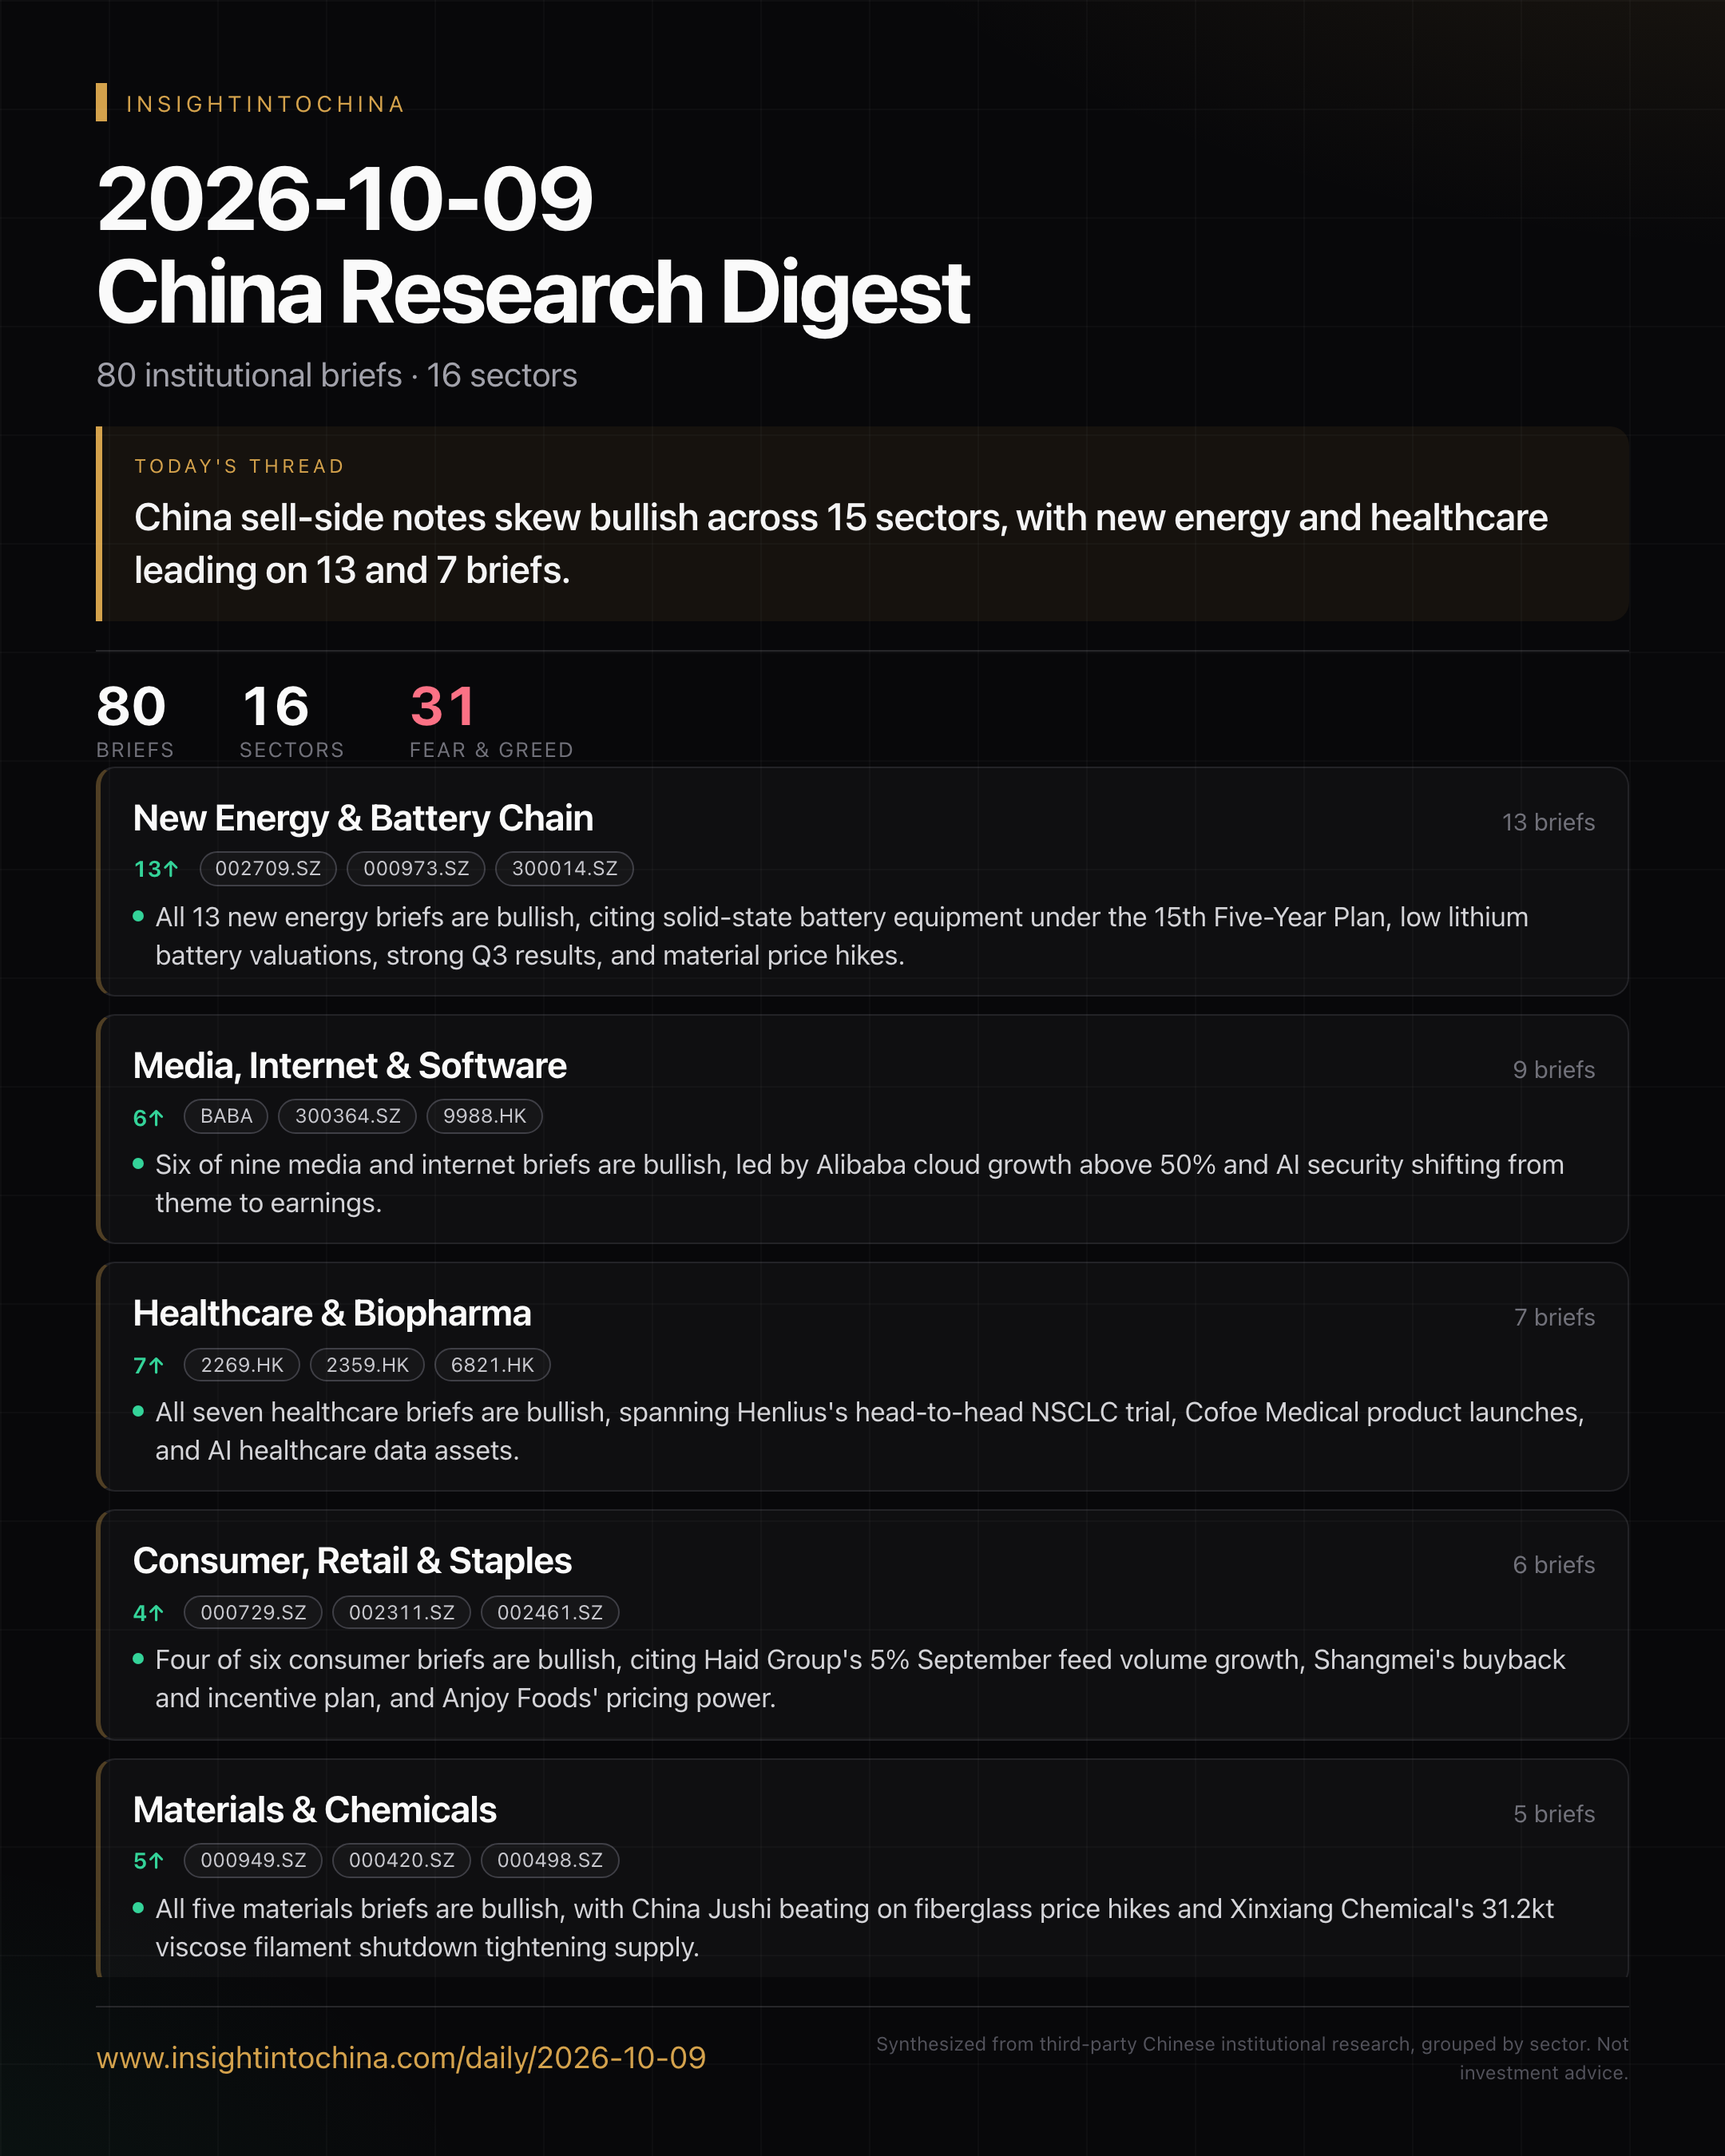
Dongwu Machinery is bullish on solid-state battery equipment suppliers, citing China's new 15th Five-Year Plan and global progress toward commercialization by 2030.
Guojin Securities remains bullish on the lithium battery sector, expecting sustained material price hikes and policy-driven demand to support a rebound from low valuations.
CICC remains bullish on Alibaba, raising profit estimates on accelerating cloud growth and narrowing AI losses while keeping its Outperform rating and target prices.
Henlius is advancing a large head-to-head trial of its PD-L1/VEGF bispecific against Keytruda in first-line NSCLC, signaling confidence in its IO 2.0 strategy.
Kaiyuan Medical is bullish on Cofoe Medical, citing strong growth from new products, Philips collaboration, and ventilator expansion, with significant upside potential.
Haid Group's September feed volumes met expectations, and its competitive moat should drive further market share expansion despite weak downstream prices.
Tianfeng reiterates a bullish view on China Jushi, citing accelerating profit growth, sustained fiberglass price increases, and structural upgrades that open a second growth curve.
The broker is bullish on the viscose filament sector due to capacity reductions and robust export demand, highlighting Xinxiang Chemical and Jilin Chemical as key beneficiaries.
The broker is bullish on Xinxiang Chemical Fibre and the viscose filament sector, citing capacity cuts and resilient demand that should keep prices and margins elevated.
Guojin Metals is bullish on Chinese gold stocks, expecting a repeat of July's outperformance driven by real interest rate pullback, European fiscal risk hedging, and returning Chinese demand.
Huachuang reiterates a Strong Buy on YTO Express, citing three underappreciated strengths—AI-driven cost reduction, franchisee ecosystem balance, and international air cargo potential—with 39% upside.
The broker is bullish on the electronic fabric sector, expecting continued price increases through Q4 2026 and into early 2027, driven by strong demand and supply constraints.
The US PCB procurement ban is a sentiment-driven overreaction; the broker recommends buying the dip in PCB stocks, which remain a core overweight in the electronics sector.
Yangjie Technology's Q3 earnings confirm a high-growth trajectory in power semiconductors, with automotive and SiC businesses doubling, supporting a bullish outlook.
Tianfeng recommends Huada Empyrean as a key beneficiary of China's EDA localization trend, with the strategic investment strengthening its digital full-flow capabilities.
Zhongtai Securities is bullish on the SOFC industry chain, seeing it as a key beneficiary of AI-driven power shortages, with Bloom Energy and its suppliers poised for growth.
Broker turns bullish on the humanoid robot sector, citing Tesla's Optimus acceleration and identifying key Chinese component suppliers as beneficiaries.
The broker maintains a bullish stance on Hengli Heavy Industry, viewing the recent price weakness as temporary and driven by sentiment, with substantial growth prospects from capacity expansions and strong industry fundamentals.
The joint statement provides a short-term reprieve for Chinese PHEV exporters, but the trade dispute is not fully resolved and further barriers may emerge.
Barclays remains bearish on European autos, seeing China's export-driven cost advantage as an irreversible threat despite potential near-term EU trade defenses.
Morgan Stanley remains bullish on the CPO test and equipment supply chain, recommending buying on dips, but downgrades FOCI due to intensifying FAU competition.
Sieyuan Electric is well-positioned for sustained growth, with overseas orders surging and new products gaining traction, making it a compelling investment at current valuations.
Jingwang Electronics is positioned as a strong alpha play in the PCB sector, with dual growth drivers from AI product ramp-up and core business price hikes, supporting continued high growth.
Tone percentile minus 20-day return percentile. Positive means the research
reads more positive than the price has been — it does not say which one is right.